Retirement Strategies That Maximize Income, Eliminate Risk, and Help Ensure You Never Run Out of Money How to Achieve The Retirement Future Everyone Seeks
Most retirement plans are built on assumptions that no longer hold up—market averages, predictable tax rates, and the belief that time will always recover losses. But as you approach or enter retirement, the rules change. What worked during your accumulation years can become a liability during the withdrawal phase.
This blog is designed to help you rethink traditional strategies and discover a more engineered approach to retirement income—one focused on certainty, efficiency, and control.
Here, you’ll learn how to reduce or eliminate the biggest threats to your financial future, including market losses, rising taxes, hidden fees, and the silent erosion caused by lost time. We break down complex financial concepts into clear, actionable insights so you can make better decisions about your 401(k), IRA, and retirement income strategy.
You’ll also discover why many conventional approaches—like relying on average returns or the 4% rule—can expose you to unnecessary risk, especially when withdrawals begin. Instead, we explore strategies designed to protect your principal, improve compounding efficiency, and create predictable income streams that last.
Our focus is on helping you transition from “assets at risk” to a more stable and structured approach using fully performing assets—where growth, income, and protection work together instead of against each other.
Whether you’re still working or already retired, the goal is simple:
help you keep more of what you earn, generate more reliable income, and build a plan that doesn’t depend on hope, timing, or market luck.
If you’ve ever wondered:
* How to create tax-efficient retirement income
* How to avoid sequence of returns risk
* How to reduce fees and increase net returns
* How to design income that doesn’t run out
—you’re in the right place.
Explore the articles below and start building a retirement strategy based on engineering, not guesswork.
Retirement Planning Math: Focus on Addition and Multiplication
The Visual Mathematician’s Rule: Why Retirement Should Only Be Addition and Multiplication
One of the fastest ways to uncover hidden risk is to take our 7 Question Retirement Stress Test.

Start here: See what your retirement actually looks like → 👉 Book Your Million Dollar Hour™
The Math of No: Why Your Retirement Plan Should Only Ever Use Addition and Exponentials
If you’re a "visual mathematician," you see the world a bit differently than most. You don't just see numbers on a screen; you see vectors, slopes, and the structural integrity of a system. When you look at a retirement plan, you aren't looking for "hope" or "potential upside." You are looking at the fundamental arithmetic operations being applied to your life’s work.
And here is the uncomfortable truth: Most retirement "strategies" sold on Wall Street today rely heavily on two operations that have absolutely no business being in your future: Subtraction and Division.
In any other engineering discipline, whether you’re building a bridge or a rocket, if your math allows for "leaks" or "structural collapses," the project is considered a failure before it even starts. Yet, in the world of financial planning, we’ve been trained to accept negative numbers as a "natural part of the cycle."
It’s time to stop being a passive participant in a broken system and start being the architect of an engineered one. To do that, we need to enforce a new rule: Your retirement math should only ever consist of Addition, Multiplication, and Exponentials.
The Forbidden Operators: Subtraction and Division
Most "Quiet Builders", those of you who have worked hard, saved well, and are now looking at the finish line, feel a sense of unease. That fatigue isn't from the work; it’s from the realization that you are playing a game where the rules are designed to extract value from you.
Subtraction: The Gift of Loss
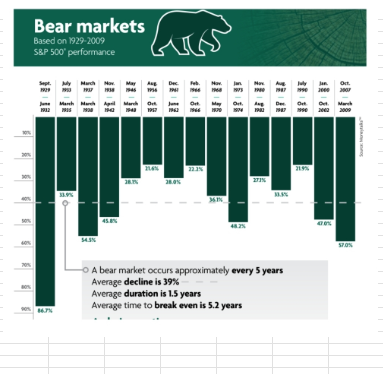
Wall Street is the only place on Earth where a 30% loss is treated as "market volatility" rather than a catastrophic failure. In the visual mathematician’s world, a negative number is a "minus" on your timeline. It is time you can never get back.
We call this the Math of Recovery. If your portfolio drops by 30%, you don’t just need a 30% gain to get back to even. You need a 42% gain just to return to your starting point. That gap is the "Volatility Recovery Analysis" that most brokers conveniently forget to mention. Subtraction kills the power of compounding. It resets the clock and forces you to spend your most valuable asset, time, just trying to break even.
And here is where many savers get fooled: routine 401(k) and IRA contributions can create a numbing effect. Fresh deposits keep landing in the account, so the decline gets visually blurred. You don’t always feel the loss in your bones because new money is masking the damage. The balance may look "not too bad" for a while, but that does not mean the underlying loss disappeared. It just means the pain has been anesthetized by contributions. Eventually, the masking stops working, and you are left waiting for the shoe to drop.
Division: The Silent Partners
Then there is division. This is the act of giving away "partnerships" in your wealth to people who didn't help you build it. When you look at your statements, you see the "leaks."
The IRS: Taking a massive slice of your harvest through deferred tax liabilities.
The Brokers: Taking their percentage regardless of whether you made money or lost it.
The Hidden Fees: The "friction" that divides your total value into smaller and smaller pieces.
If your strategy allows for division, you aren't the sole owner of your retirement. You are a minority shareholder in your own life.
The 2x, 3x, 5x Loss Trap
This is where the math gets ugly. Over a lifetime, the accumulation of losses and the gains required to recover from those losses can eventually exceed your total contributions by 2x, 3x, or even 5x—if you're lucky. If you're unlucky, you can lose more than you ever put in. That is not a strategy. That is a slow bleed dressed up as sophistication.
This is the part most people never calculate because the statement only shows a moment in time. It does not show the lifetime cost of repeatedly falling in a hole and then spending years climbing back out. Every loss creates a new recovery burden. Every recovery burden steals future compounding. Over time, the leaks become larger than the contributions, and the client is left doing all the saving while the system does all the siphoning.
We call this The Wall Street Mixer: a system designed to keep your money moving so they can take it home. More movement means more fees, more friction, more taxable events, more exposure, and more excuses. Wall Street is not doing this for the client’s benefit. The client is the fuel for their wealth. The proof is not in the marketing. The proof is in the math of the leaks.
Why Do We Accept the "False Model"?
Wall Street operates on a "False Model" driven by the twin engines of Greed and Fear. They use hidden complexity to keep you addicted to the daily news cycle, buying and selling, chasing the next "big thing." They want you to believe that "Participation" in the market is the only way to grow.
But Participation is just a polite word for gambling with your future.
The visual mathematician demands Engineered Performance. Think of it this way: Traditional retirement products (stocks, bonds, real estate) are "single-pillar" assets. They do one thing, and they usually come with a side helping of risk. It’s like carrying around a pager, a calculator, and a separate camera in 2026. It’s a Rolodex strategy in a SpaceX world.
We believe in the Consolidation of Technology. Just as your smartphone merged a dozen devices into one high-performing tool, Fully Performing Assets (FPA) consolidate 5 to 15 "pillars" of value into a single vehicle. At the core, an FPA is designed with a Guaranteed Present Value (GPV), a Guaranteed Future Value (GFV), and Uncapped Gains. In plain English: you know there is protected value now, engineered value later, and growth potential without volunteering for subtraction. We’re talking about growth, protection, tax-free income, and A+ guarantees, all working simultaneously.
Here’s where the SpaceX World metaphor matters. Wall Street still runs a Disposable Rocket model. They launch your gains into the sky during the good years, then dump them in the ocean during every major market crash and call it normal. That is not engineering. That is waste.
The SpaceX Model of Fully Performing Assets works differently. Just as SpaceX removed subtraction by re-using boosters and relighting engines for a safe landing, our strategies are built to remove the subtraction of market losses. We don’t dump your gains in the Wall Street ocean; we refuel them for the next stage of growth. What the old model called "impossible" for 50 years, the Visual Mathematician proved could be done by changing the architecture, not by wishing harder.
Wall Street has its own version of a guarantee, but it’s the one they never say out loud: the hidden guarantee of eventual loss. If you stay exposed long enough, some percentage of your money will get cut down in the next correction, bear market, or sequence hit. That is the part their brochures whisper around. On Your Street, the value of the position is greater than anything Wall Street has ever known, because the architecture starts with protection and then layers growth on top, instead of sacrificing one for the other.
The Math of Success: Addition and Multiplication
When we strip away the noise, a successful retirement plan focuses on only two things: keeping what you have (Addition) and growing it efficiently (Multiplication/Exponentials).
1. Addition (The Floor)
In our world, the "0%" is your best friend. In a strategy built on Your Street, when the market drops 30%, your account does exactly... nothing. You stay at zero. You don't lose a penny. This is the "Engineered Certainty" that allows for continuous addition. Every year you have a gain, it is "locked in." It becomes the new floor. You are only ever adding to the pile, never subtracting from it. That is the difference between a visible guarantee and a hidden one. Wall Street’s hidden guarantee is loss. Your Street’s visible engineering is GPV, GFV, and a floor that refuses to give your time back to the market.
2. Multiplication (Uncapped Gains)
Many brokers will try to scare you away from safe-money strategies by claiming they have "caps" that limit your growth. This is a myth we enjoy debunking. Through Uncapped Gains (UCG) and Expanded Market Participation (EMP), we can actually engineer a multiplier effect.
Imagine a 110% to 200% multiplier on the market’s performance. If the market goes up 10%, your "multi-pillar" asset could potentially capture 11% to 20% of that growth, all while maintaining a 0% floor against losses. That is the visual mathematician’s dream: upside multiplication with a total ban on subtraction.
The Margin Audit™: Finding the Leaks
Most people can't say "no" to bad financial advice because they haven't verbalized the rules they want for their retirement. If you don't have a rulebook, you take whatever you can get: and you usually get what you don't understand.
Learning adds exponential value. When you understand the "Sequence of Return Margin" and how it affects your "Compounding Efficiency," you stop being a victim of market cycles and start being a commander of your capital.
This is why we perform a Margin Audit™. We look for the hidden subtractions and divisions that are draining your tree of retirement before the fruit has a chance to ripen. We aren't looking at "macro headlines"; we are looking at the micro margins that determine whether you retire with peace or with a prayer.
The Architect vs. The Participant
The difference between a "Participant" and an "Architect" is simple:
The Participant hopes the market stays up. They accept subtraction as a rule. They are uneasy, fatigued, and waiting for the shoe to drop.
The Architect designs a system where subtraction is impossible. They use institutional-grade Asset Liability Management (ALM) to ensure that their money follows their rules, in their time, on their street.
Peace is the path, and wisdom is the way. But wisdom requires action. You cannot "hope" your way into a math-based retirement. You have to engineer it.
Your Million Dollar Hour™
For the Quiet Builder who is ready to move beyond the noise of Wall Street, we offer the Million Dollar Hour™ Forecast. This is not a "free consultation" or a sales pitch disguised as a chat. This is a $995 professional engineering session designed for high-intent individuals who want a scrutinized, certain plan.
During this 60-minute session, we apply the Visual Mathematician’s Rule to your specific situation. We run the 7-Question Stress Test to see exactly where your current plan is leaking and where we can apply Level Yield Amortization to "heal" your balance sheet.
We look at:
Growth Test: Are your gains actually yours, or are they "on loan" from the market?
Tax Test: How many "silent partners" are waiting to divide your harvest?
Protection Test: Is your floor reinforced with A+ guarantees, or is it made of paper?
Schedule your Million Dollar Hour™ here.
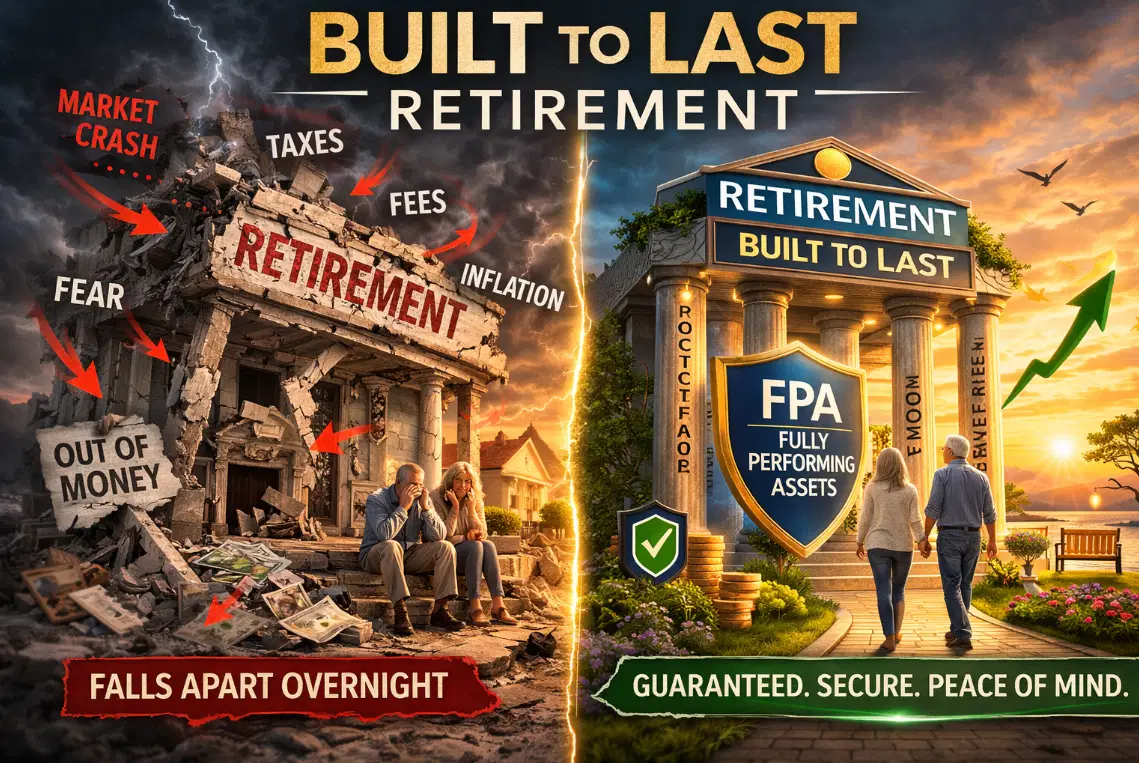
If you are tired of the "spinning sharp knives" of interest-rate ripples and market volatility, it’s time to change the math. Stop accepting subtraction. Stop allowing division. Focus on the addition and multiplication that creates true, generational wealth.
Your money. Your rules. In your time. On your street.
Ready for clarity instead of confusion?
The Million Dollar Hour™ is your educational, one-on-one retirement review that reveals where your plan leads — not just where it’s been.
👉 Schedule your session today.
Concerned about market losses, taxes, or income reliability?
Take the 7 Question Retirement Stress Test →
You can keep participating… Or you can finally see the outcome. The Million Dollar Hour™ shows you exactly:
✔ Where you are ✔ Where you’re going ✔ How to fix the gaps 👉 Book your session now