Six Inspection Test Screening Tells You What Looks Right
Six Retirement Inspection Tests
Author: Frank L Day
The Six Retirement Inspection Tests: Screening Tells You What Looks Right, Not What Actually Works

No hype. No universal guarantees. No promise that one strategy will fit every person.
Inspection does not manufacture safety. It does not guarantee an outcome. It determines which rules actually hold for this individual, under this law, with these terms, across this time horizon.
I only promise the truth. Nothing more.
Most tests tell you whether something appears acceptable. Retirement requires determining whether it is actually capable of performing its job over time.
That distinction is not about intelligence, effort, or good intentions. It is about which instrument you use and at what resolution it measures.
A retirement strategy may look organized, sound persuasive, feel reasonable, or pass a quick judgment. None of those impressions proves how it behaves when income is needed, conditions change, or withdrawals continue for decades.
The questions raised in The Questions You Never Asked About Your Retirement lead naturally to this one:
How do you inspect what you expect?
The Six Retirement Inspection Tests
The Four Screening Tests
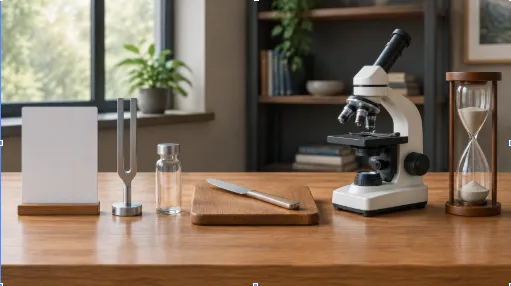
The eye, ear, smell, and thumb tests are screening tests.
They can tell you:
> “Something looks right.”
They can also tell you:
> “Something does not feel right.”
Those signals matter. They may tell you to continue, pause, or ask a better question. But they cannot tell you whether the architecture is capable of performing its job over time.
The stronger requirement is:
> “Show me exactly how this works, what it costs, what risks it carries, what job each component performs, and what happens over time.”
An impression suits a presenter because an impression cannot be falsified. A feeling cannot be cross-examined. A statement may sound complete while leaving the assumptions, limitations, costs, and failure points unexamined.
Screening tests are not useless. They are insufficient. They were never designed to produce evidence.
For the deeper examination of granular inspection and sequencing, see The Microscope Test. The point is not to assume that a current strategy is wrong. The point is to determine what can actually be known about it.
The Microscope Test: Inspection at Retirement Granularity
The microscope does not simply ask, “Is this retirement strategy good?”
It asks structured questions at the level where the decision is actually made.
Structure and Components
What is actually inside the strategy?
What assets are being used?
What job is each asset expected to perform?
Risk and Cost
What risks are being assumed?
What fees are being charged?
What taxes can occur, and where can losses occur?
Income
How is income generated?
How dependable is that income under the conditions that matter?
Behavior Under Stress
What happens during withdrawals?
What happens during market declines or when interest rates change?
Resilience
What happens to purchasing power?
What happens to liquidity and legacy?
Dependencies and Failure Points
Where are the dependencies?
Where are the hidden costs?
What are the single points of failure?
Apply OOM™ (Odds, Opinions, Models) to separate what is probable, what is merely being asserted, and what happens when a model is stressed.
Then use the FBS Conjecture™ as a testable question, not a conclusion:
For this individual, with these resources, terms, costs, and time horizon, which architecture can produce the most reliable and repeatable required outcome?
A belief has no failure mode. A model does.
That is inspection at retirement granularity.
The microscope does not make a current plan wrong. It makes the plan inspectable.

The Time Test: Testing the Architecture Across the Horizon
An automobile engine can be inspected perfectly, and that inspection still tells you nothing about how the engine performs after 100,000 miles.
Retirement carries the same problem.
A strategy may appear sound at the beginning. The real question is whether it continues performing after years of withdrawals, inflation, tax changes, market movement, health events, and changing family needs.
The microscope alone is not enough.
Year 1 → Year 5 → Year 10 → Year 20 → Year 30
Test the architecture across these conditions:
Market decline
Inflation
Interest-rate changes
Tax changes
Withdrawals
Longevity
Unexpected expenses
Changing income requirements
Sequence of returns
The Time Test measures durability. It is not a forecast and not a prediction.
> “Does the architecture continue doing its intended job as time passes and conditions change?”
The cost of waiting to learn also belongs in the test. Do Nothing Cost? Three Questions of Retirement Inaction examines why delay is not empty space.
Time cannot be refunded.
The Two Tests of Time: Constraint and Instrument
The Clock Test is the constraint.
Time runs whether or not anyone chooses it. It does not measure anything. It does not pause for reconsideration. It answers only:
When must this be done?
The answer is: before the consequence arrives.
The Time Test is the instrument.
It is operated deliberately across a defined horizon. It answers:
What does time do to this architecture?
The working order is simple:
The microscope runs inside the window, the Time Test runs across the window, and the Clock Test arrives on its own.
The Clock Test is a constraint, not one of the six inspection instruments. That is why it is described here rather than listed in the table.
The microscopic test comes before the clock test, and before time runs out.
Inspect What You Expect™: The Hierarchy
Use the tests in order. Each answers a different question:
Eye Test: What does it look like?
Ear Test: What am I being told?
Smell Test: Does something seem wrong?
Thumb Test: What is my quick judgment?
Microscope Test: What is actually happening inside?
Time Test: What happens when I let it operate?
The first four screen. The final two produce evidence.
> Retirement is too important to inspect with only your eyes, ears, nose or thumb. You need the granularity of a microscope and the reality of time.
MICROSCOPE × TIME
Inspect the architecture.
Test the components.
Stress the assumptions.
Run the scenarios.
Observe the consequences over time.
Then determine what needs to change.
Screening tests tell you how something appears. The Microscope Test tells you what is actually inside it. The Time Test tells you what happens when it operates across decades and changing conditions.
Only together do they produce evidence of a reliable, repeatable, and reusable future.
Reliability means producing a required outcome.
Repeatability means continuing to produce that outcome across different conditions.
Reusability means using the tested architecture again as circumstances change, rather than starting from an unexamined assumption each time.
Why This Connects to Engineering, Not Products
This belongs to an engineering philosophy rather than a product philosophy.
Do not simply ask whether your retirement strategy looks good today. Inspect what you expect, and test whether it can continue doing its job tomorrow.
Ask what the architecture must produce. Then test whether it can produce it.
The operating process is:
QUESTION → TEST → PROVE → DECIDE → ACT
“No change is warranted” is a legitimate and valuable outcome. If inspection confirms that the current architecture fits the requirements, that conclusion has value.
A test that can only recommend change is not a test.
Use RID — Require, Insist, Demand:
Require visible assumptions.
Insist on actual terms.
Demand a testable outcome.
Use PxRxT — Principal × Rate × Time. A 30% loss reduces $100 to $70. Returning from $70 to $100 requires approximately a 42.9% gain. That is The Math of Recovery, not a forecast.
Use TCO — Total Cost of Ownership. Include loss, time, taxes, inflation, volatility, fees, sequence risk, opportunity cost, and delay.
Delay is a line item, not empty space.
The Engineered Retirement Blueprint provides the accounting structure:
Balance Sheet = Source of Funds
Income Statement = Uses of Funds
Margin = The Battleground
Use The Margin Audit™ to inspect what remains after the architecture encounters its real costs.
Financial Gravity includes six Wealth Killers:
Taxes
Fees
Market Volatility
Inflation
Complexity
Poor Income Design
Think of these as gears that can make the Pillar gears turn backward. The engineering objective is to identify a harmful gear and determine whether it can be disengaged, reduced, or redesigned.
The Retirement Stress Lab examines:
Equity, Income, Time, Inflation, Taxes, Events, Longevity, Legacy.
The Retirement Alternative Test™ follows this sequence:
Existence → Testability → Evidence
Then apply the LESS, MORE, and EXPONENTIAL thresholds. Ask whether an alternative may create less unwanted exposure, more of a required outcome, or exponential improvement by coordinating functions that are otherwise disconnected.
This is Participation vs. Engineered Performance. Participation observes activity. Engineered Performance tests behavior.
It is also the difference between a Shiny Object vs. Dark Object. The Shiny Object is the attractive headline, average, or projection. The Dark Object is the total cost, interrupted time, sequence risk, taxes, fees, and changing conditions beneath it.
Serve The 7 Disciplines of Retirement Wealth™ and The 9 Levels of Retirement Discovery™. Preserve, Protect & Prolong.
The Three Streets clarify the assignment:
Wall Street can provide products.
Main Street contains life’s demands.
Your Street asks what architecture belongs between resources and required outcomes.
The primary question remains:
> What income, protection, liquidity, growth, tax, flexibility, and legacy outcomes must this retirement architecture produce, and what evidence supports that conclusion?

A retirement plan should be tested before it is trusted. The Million Dollar Hour™ is an educational comparison laboratory for examining assumptions, requirements, terms, costs, income needs, liquidity, and stress conditions.
Bring your assumptions, account statements, income needs, tax concerns, benefit information, liquidity requirements, family priorities, and legacy goals. Test the destination before you trust the journey.
Don't Wait. Don't Delay. Don't Hurry.
Some Money, Same Time. Different Rules. On Your Street. Different Outcomes.
It is double-digit opportunity standing on a foundation of reliability. The foundation question comes first.
The Standard of Evidence
Constant learning is part of stewardship. Learn what the architecture does. Unlearn assumptions that fail inspection. Seek wisdom before consequences become the teacher.
A rouge appearance of preparedness is not evidence of a tested retirement architecture.
Inspect what you expect.
Do not test the promise. Test the behavior. Show the outcome. Show the total cost. Show what happens if expectations fail.
A valid retirement architecture must be capable of being inspected, stressed, observed, and reconsidered. It must also be allowed to pass without change when the evidence supports that conclusion.
The Complete Test
> What does the eye see? The shape, not the arithmetic.
>
> What does the ear hear? The confidence, not the terms.
>
> What does the smell register? That something is off, without naming what.
>
> What does the thumb decide? Where to cut the butter.
>
> What does the microscope show? What is actually inside, at the level where the decision is made.
>
> What does time reveal? Whether it can keep doing its job.
Test before you trust.
Why accept uncertainty without a defined upside when you can compare it with approaches that may offer contractual certainty and defined upside—subject to the actual terms, limitations, costs, and claims-paying ability?
This article is for educational purposes only; not individualized financial, tax, legal, or investment advice; no universal guarantees; contractual guarantees subject to actual terms, limitations, costs, exclusions, restrictions, and claims-paying ability; illustrations are not forecasts; consult qualified professionals; plan rules and tax treatment vary; and a retirement strategy must be testable to be valid.

