Misinformation Ledger™ Every Instrument Reveals Something
Misinformation Ledger
Author: Frank L Day
The Misinformation Ledger™: Every Instrument Reveals Something and Hides Something

No hype. No universal guarantees. No promise that one strategy will fit every person.
Inspection does not manufacture safety. It does not guarantee an outcome. It determines which rules actually hold for this individual, under this law, with these terms, across this time horizon.
I only promise the truth. Nothing more.
Every test produces information.
Every test can also produce misinformation.
Retirement decisions are often inspected with instruments that were never designed to answer the retirement question at the required resolution. The problem is not simply that the information is incomplete. The instrument manufactures a specific kind of false knowledge.
Nobody necessarily has to lie. The instrument itself can create the impression. And when an impression is mistaken for evidence, the consequence may not appear until years later.
The questions raised in The Questions You Never Asked About Your Retirement lead to a more precise question: What does the instrument reveal, and what does it hide?
The Seven Instruments
Why the Clock Test Appears Here
The companion article on the six inspection tests describes the Clock Test as a constraint rather than one of the six inspection instruments. That remains true.
This ledger includes it anyway for a specific reason: the Clock Test is the only instrument in the set that produces misinformation without producing information.
Every other instrument reveals something and distorts it. The Clock Test reveals nothing, measures nothing, and still manufactures the belief that waiting is neutral. That is a different category of error, and it is why the ledger has seven rows while the inspection taxonomy has six instruments.
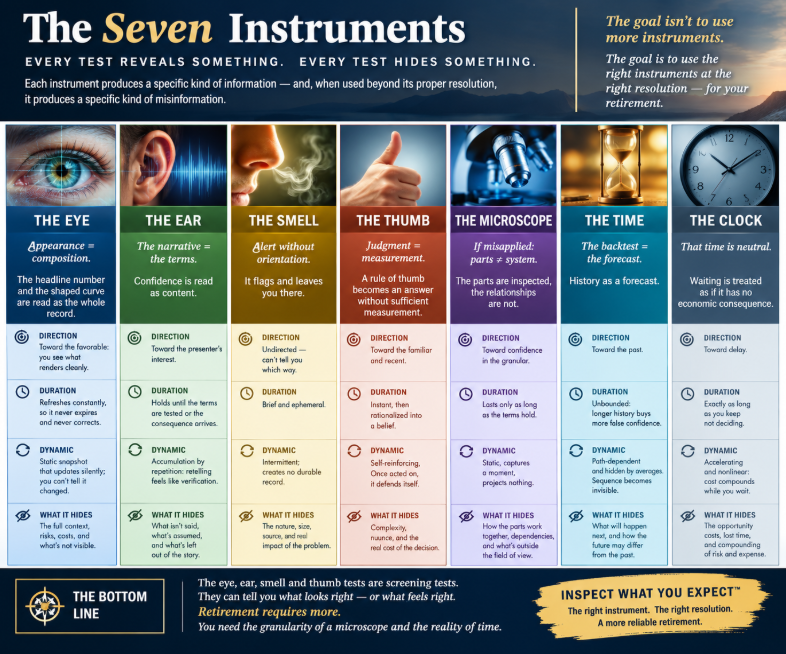
The seven rows correspond to The Seven Instruments™, the series framework and visual hub grid that shows each instrument's direction, duration, dynamic, and what it hides. This ledger is the written counterpart to that grid. The grid shows what each instrument hides. This article examines why the error holds, and how long it lasts.
The Direction Test
Direction tells the story. A screening instrument does not merely show information. It can bias the interpretation of information.
The Eye favors what is visible. The Ear favors what is confidently communicated. The Smell produces suspicion without necessarily producing direction. The Thumb favors familiarity and immediacy. The Microscope can favor whatever has been selected for inspection. The Time Test can favor the historical record.
The Clock exposes something different: the cost of waiting.
The six-test taxonomy helps establish the inspection foundation, but this ledger extends it by asking what each instrument causes the observer to believe.
> What does this instrument cause me to believe, and what does it prevent me from seeing?
“Is this information accurate?” is important, but it is not sufficient on its own.
Duration Is the Killer
Misinformation does not necessarily have a shelf life. It can have an arrival date.
A retirement assumption may remain comfortable for years. Then the consequence arrives:
A sequence of returns
A tax bill
An income shortfall
A liquidity problem
A prolonged inflation period
A market decline during withdrawals
A change in interest rates
A longevity event
The information did not suddenly become wrong. The consequence finally arrived.
> The expiration of an assumption can be the moment its cost becomes largest.
That is why the cost of doing nothing belongs in the inspection. TCO — Total Cost of Ownership includes loss, time, taxes, inflation, volatility, fees, sequence risk, opportunity cost, and delay. Delay is a line item, not empty space.
The Detectability Problem
Can an instrument detect its own error? Usually, the answer is limited.
The Eye cannot easily detect an error created by the Eye. The Ear cannot independently cross-examine its own narrative. The Smell can signal a problem without identifying it. The Thumb can reinforce the judgment it already made. The Microscope can provide extraordinary detail while missing relationships outside its field of view. The Time Test can demonstrate what happened historically without demonstrating what will happen next.
The corrective instrument must be different from the instrument that created the impression.
You do not solve every measurement problem by looking harder through the same lens. Sometimes you need a different lens.
That is the operating discipline: QUESTION → TEST → PROVE → DECIDE → ACT.
Use RID — Require, Insist, Demand: Require visible assumptions. Insist on actual terms. Demand a testable outcome.
Use OOM™: Odds, Opinions, Models. A belief has no failure mode. A model does.
Use the FBS Conjecture™ as a testable question rather than a conclusion.
Attribution
An impression is difficult to cross-examine. Who is responsible for the conclusion?
The person who presented the number
The person who selected the comparison
The person who chose the time period
The person who created the projection
The investor who accepted it
The model, the market, the product, the advisor, and the company may also become candidate answers. The answer can become surprisingly difficult.
That is why retirement inspection should document:
Assumption → Measurement → Test → Result → Consequence
rather than:
Claim → Belief → Action
Agency
> Who benefits if the existing impression continues?
That does not automatically mean someone is acting improperly. It means incentives matter.
A retirement inspection should separate:
Who provides the information?
Who benefits from the decision?
Who bears the risk?
Who bears the cost?
Who controls the outcome?
Those are not necessarily the same person.
Reversibility
Some mistakes can be corrected, but correction does not necessarily restore the time or money already consumed. You can change a portfolio, an allocation, a product, or an income strategy, but you cannot repurchase yesterday.
This is where the Clock Test becomes fundamentally different.
> A late correction may repair the strategy without repairing the opportunity that was lost while the error persisted.
Use PxRxT — Principal × Rate × Time. The relationship is simple; the consequences may not be. The Math of Recovery shows why a 30% loss requires approximately a 42.9% gain merely to return to the starting point.
Time cannot be refunded.
Scaling
Misinformation scales particularly well when it can be compressed into an average:
One number
One chart
One percentage
One historical return
One rule of thumb
One headline
One story
The easier information is to repeat, the easier it is to distribute. Repetition can create familiarity without creating evidence.
> Repeatability of a claim is not the same thing as reliability of the outcome.
The Shiny Object may be an average return or attractive projection. The Dark Object may include the Wall Street Cycle, routine market swings, sequence risk, fees, taxes, inflation, and lost time. A $100,000 contribution history can, under some conditions and definitions, be associated with a 5x Accumulated Loss experience: $500,000 in cumulative losses, missed growth, and recovery demands. That is an illustration to test, not a conclusion about every investor.
The Retirement Inspection Problem
Retirement requires more than knowing what happened:
What happened
Why it happened
What relationships produced it
What it cost
What could change it
What happens when withdrawals begin
What happens when conditions change
What happens over time
The market may move through 10–20% swings during recurring cycles, while larger retractions can disrupt a retirement sequence. The point is not to predict the next event. The point is to test whether the architecture can perform when conditions change.
> Can the expected retirement outcome continue to perform its intended job under changing conditions?
MICROSCOPE + TIME
Microscope
Inspect the components. Identify the assumptions. Expose the costs. Examine the relationships. Find dependencies. Identify vulnerabilities.
For a deeper treatment of granular inspection and sequencing, read The Microscope Test.
Time
Run the architecture through different conditions. Observe sequence. Measure withdrawals. Test compounding. Test longevity. Test inflation. Test taxes. Test market disruption. Test changing interest rates.
Reliability means producing a required outcome. Repeatability means continuing to produce it across different conditions. Reusability means using a tested architecture again as circumstances change.
> What survives the test?
The Engineered Retirement Blueprint provides the accounting structure: Balance Sheet = Source of Funds; Income Statement = Uses of Funds; Margin = The Battleground.
Financial Gravity includes six Wealth Killers: Taxes, Fees, Market Volatility, Inflation, Complexity, and Poor Income Design. Think of them as gears that can make the Pillar gears turn backward.
Different resources may perform different jobs, and whether those jobs are coordinated is a condition to test rather than assume.
The Purpose of the Ledger
The purpose of the ledger is not to accuse anyone of lying. It is to identify the type of error an instrument can manufacture when used beyond its proper resolution.
That changes the question from:
> “Who is telling me the truth?”
to:
> “What instrument am I using to determine what is true?”
The wrong instrument can produce a convincing answer. And a convincing answer can still be wrong.
This is Participation vs. Engineered Performance. Participation observes activity. Engineered Performance tests behavior.
The Retirement Stress Lab examines Equity, Income, Time, Inflation, Taxes, Events, Longevity, and Legacy. The Retirement Alternative Test™ follows Existence → Testability → Evidence, then applies the LESS, MORE, and EXPONENTIAL thresholds.
“No change is warranted” remains a legitimate outcome. A test that can only recommend change is not a test.
The Three Streets clarify the assignment: Wall Street can provide products. Main Street contains life’s demands. Your Street asks what architecture belongs between resources and required outcomes.
The work serves The 7 Disciplines of Retirement Wealth™ and The 9 Levels of Retirement Discovery™. Preserve, Protect & Prolong.

The primary question remains:
> What income, protection, liquidity, growth, tax, flexibility, and legacy outcomes must this retirement architecture produce, and what evidence supports that conclusion?
The Million Dollar Hour™ is an educational comparison laboratory for examining assumptions, requirements, terms, costs, income needs, liquidity, and stress conditions.
Bring your assumptions, account statements, income needs, tax concerns, benefit information, liquidity requirements, family priorities, and legacy goals. Test the destination before you trust the journey.
Don't Wait. Don't Delay. Don't Hurry.
Some Money, Same Time. Different Rules. On Your Street. Different Outcomes.
It is double-digit opportunity standing on a foundation of reliability. The foundation question comes first.
INSPECT WHAT YOU EXPECT™
Don't simply look. Inspect.
Don't simply listen. Test.
Don't simply sense. Measure.
Don't simply judge. Compare.
Don't simply examine the parts. Examine the relationships.
Don't simply study history. Stress the future.
And don't assume time is waiting for you. Measure what time is doing while you decide.
A rouge appearance of preparedness is not evidence of a tested retirement architecture.
Inspect what you expect.

The Closing Standard
Every instrument reveals something.
Every instrument hides something.
Know what it reveals.
Know what it hides.
Then choose the instrument capable of inspecting what you actually expect.
Test before you trust.
Why accept uncertainty without a defined upside when you can compare it with approaches that may offer contractual certainty and defined upside—subject to the actual terms, limitations, costs, and claims-paying ability?
This article is for educational purposes only; not individualized financial, tax, legal, or investment advice; no universal guarantees; contractual guarantees subject to actual terms, limitations, costs, exclusions, restrictions, and claims-paying ability; illustrations are not forecasts; consult qualified professionals; plan rules and tax treatment vary; and a retirement strategy must be testable to be valid.

